Business insurance for couriers, delivery drivers and taxi drivers
Protect your transport business with insurance that fits
Whether you deliver parcels, drop off takeaway orders or drive a taxi, your work carries specific risks that business insurance is designed to cover. Discover Public Liability cover for your insured courier, delivery and taxi activities. It covers liability for injury or damage you cause to others in your work, subject to the policy's conditions. Damage caused with or by a vehicle you drive or use is excluded, except damage caused by items being loaded onto or unloaded from it. Your vehicle needs its own motor insurance.
Business insurance, done differently.

Fully online business insurance in Ireland.

A few questions and you're covered.

No lock-in, no long contracts.

Excess from €0, up to €6.5 million of cover.
Our insurance is for

Why business insurance is essential in transport and logistics
Delivery and driving work puts you on other people's property several times an hour. From a doorstep handover to a visit to your depot, these activities share common exposures:
Injury to other people: a pedestrian tripping over parcels during a drop.
Damage at a delivery address: a door, floor or fitting marked while you carry goods in.
Accidents at your own premises or depot: a visitor slipping, or something falling.
Damage to goods in your care: an item damaged while you handle it, within the included cover for property in your care and its limits.
One thing to keep separate: damage caused with or by a motor vehicle you drive or use is excluded from Public Liability. The exception is damage caused by items being loaded onto or unloaded from the vehicle. Your vehicle needs its own motor insurance. Public liability covers eligible non-motor business claims, subject to the policy terms.
What is Public Liability insurance?
How does public liability work? If a third party, like a client or a member of the public, holds you responsible for an injury or for damage to their property, Public Liability insurance takes care of your defence costs and any compensation due.
What does it cover? Injury or property damage caused to others through your insured courier, delivery or taxi work. Choose €1.25 million, €2.5 million or €6.5 million per claim. Included cover for property in your care applies to defined handling damage to third-party property, up to €5,000 per claim and €10,000 per insurance year. The endorsement's conditions apply. You can add employers' liability for staff, up to €13 million per claim and per insurance year.
What is not covered? Damage caused with or by a motor vehicle you drive or use (except damage caused by items being loaded or unloaded), and loss or disappearance of property. The included custody cover is not a promise to insure every parcel or every loss in transit. Check the cover for the goods and work you handle before taking on a delivery contract.
Cover that fits your profession. You describe your activities fully at sign-up, and your cover matches what you actually do: whether that's delivering parcels, couriering goods across the city or carrying passengers as a taxi driver.
Your excess. The amount you pay yourself towards a claim. The options are €0, €250, €500, €1,000 and €2,500, with €0 and €250 available up to €500,000 annual revenue; above that the minimum is €500. A higher excess means a lower premium.
Is it mandatory? Public Liability isn't required by law in Ireland. In practice, delivery contractors, depots and local authorities often ask for it before you can take on work. Cover starts from €7.55 per month.
Who needs it? Any courier, delivery driver or taxi driver who deals with the public: parcel and same-day delivery, food delivery, newspaper rounds, or taxi and chauffeur work.

Which cover do you need?
Most businesses are exposed to both. One covers injury and damage, the other financial loss from your work. You can combine them in one Insify policy. Cover limits, excess and exclusions apply. See the policy wording.
Public Liability insurance
Covers claims when your work injures someone or damages something that belongs to them. For example, someone trips over your equipment, or you damage a floor while working at a client's premises.
- Choose your cover: from €1.25 million up to €6.5 million per claim, and up to twice that per insurance year
- Excess from €0, depending on your turnover
- Staff? Add optional Employers' Liability with €13 million cover per claim
- Most relevant when your work brings you into contact with clients, the public, their premises or their belongings
Professional Indemnity insurance
Covers purely financial loss a client suffers through a professional mistake, oversight or wrong advice, with no injury or property damage involved. Think of work a client claims was unfit for purpose and cost them money.
- Choose your cover: from €125,000 up to €1.25 million per claim, and up to twice that per insurance year
- Excess from €0, depending on your turnover
- Most relevant when clients pay you for advice, programmes and plans
What's covered
Transport by road
Transfer of items/ goods
Transfer of people
Participation in or execution of business trips
Use of land, buildings or premises for the insured activity
Damage caused with or by a motor vehicle you drive or use. This does not apply to damage caused by items being loaded onto or unloaded from it. Each vehicle needs its own motor insurance.
Moving services
Transport by water, rail and air
Transport of animals and livestock
Private use of a company bicycle and/or storing it at your own place of residence
Cover and exclusions shown are indicative and non-contractual. Only the terms of your policy apply.
Some examples
A courier's hand truck slipped in an apartment lobby and cracked a glass entrance door and marble tiles. The damage to the building was covered by public liability.
A pedestrian tripped over parcels a courier had set down on the pavement and broke her arm. The claim for her injury was covered.
A visitor to a courier's depot trips over packaging left in a walkway and is injured. Public liability may cover the claim if the business is legally liable and the policy's conditions are met.
A courier's hand truck slipped in an apartment lobby and cracked a glass entrance door and marble tiles. The damage to the building was covered by public liability.
A pedestrian tripped over parcels a courier had set down on the pavement and broke her arm. The claim for her injury was covered.
A visitor to a courier's depot trips over packaging left in a walkway and is injured. Public liability may cover the claim if the business is legally liable and the policy's conditions are met.
Examples are for illustrative purposes only. Compensation depends on the exact circumstances of the claim. No rights can be derived from these examples.
Your business insurance with Insify SmartGuide
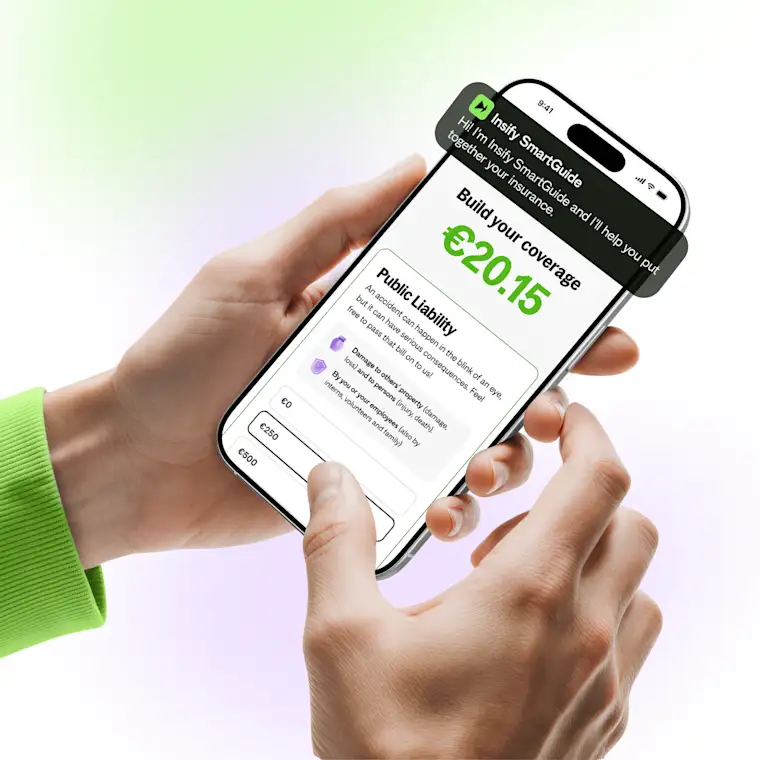
Taking out insurance can be quick. Making sure you have the right cover is another matter. With Insify SmartGuide, you don't sign a contract blindly. You ask all your questions, and get clear, immediate and personalised answers, before you take out a policy.
Are you covered if you accidentally damage a client's equipment while working?
What excess should you choose?
Are you protected in the event of a dispute with a client?
Insify SmartGuide guides you step by step to understand what's covered, what isn't, and why. In just a few clicks, you build insurance that's truly tailored to your business, with complete confidence. Try Insify SmartGuide. Understand your insurance before you need it.
More than 50,000 entrepreneurs trust us
When I had to make a claim, I was amazed how quickly and efficiently it was handled. Within a few days I had a resolution.
Very friendly, quick and thorough. It gives me real confidence in taking out the cover. The company feels genuinely transparent, exactly what I look for. You don't find that often.
Very friendly, quick and thorough. It gives me real confidence in taking out the cover. The company feels genuinely transparent, exactly what I look for. You don't find that often.
When I had to make a claim, I was amazed how quickly and efficiently it was handled. Within a few days I had a resolution.
The cover itself was sorted quickly, and when I later needed support I got that fast too.
Very friendly, quick and thorough. It gives me real confidence in taking out the cover. The company feels genuinely transparent, exactly what I look for. You don't find that often.
When I had to make a claim, I was amazed how quickly and efficiently it was handled. Within a few days I had a resolution.
The cover itself was sorted quickly, and when I later needed support I got that fast too.
Frequently Asked Questions
Public liability isn't required by law in Ireland. In practice, however, it is often required by clients, contractors, landlords and local authorities before you can take on delivery contracts or operate from a depot. Note that motor insurance for your vehicle is a separate, legally required cover: public liability does not replace it. So while the law may not force you to take out public liability, the market you work in usually will.
Public liability does not replace motor insurance. Damage caused with or by a vehicle you drive or use is excluded, on the road or parked. The exception is damage caused by items being loaded onto or unloaded from it. Your public liability policy covers eligible non-motor business liability, subject to its conditions and exclusions.
The policy includes cover for property in your care for defined damage while handling third-party property, up to €5,000 per claim and €10,000 per insurance year. The endorsement's conditions apply, and disappearance or loss is excluded. This is not a promise to insure every parcel or every loss in transit. Check the cover for the goods and work you handle before taking on a delivery contract.
Yes. Your premium and cover are based on your business's real profile: the actual premium depends on your activity, turnover, cover amount and excess. That means a self-employed courier is not priced like a delivery firm with staff. Declare your turnover accurately at sign-up so your cover matches reality.
Public Liability cover starts from €7.55 per month including taxes. The actual premium depends on your activity, turnover, cover amount and excess, so a part-time courier and a full-time taxi driver will not pay the same. You see your price online in minutes, with no obligation.