Roofer insurance
You work at height, on other people's buildings, in Irish weather. This cover handles injury and damage to property that is not yours.
Cover for roof structures, tiles, felt, skylights and dormers, on pitched and flat roofs.
Public Liability from €21.84 per month, with €2.5 million of cover per claim.
Online quote in minutes, no long-term commitment, cancel any day.


Business insurance, done differently.

Fully online business insurance in Ireland.

Answer a few questions for your quote. Cover can start tomorrow.

No lock-in, no long contracts.

Excess from €0, with €2.5 million of cover per claim and €5 million per year.
Why take out business insurance as a roofer?
Roofing puts weather, height and someone else's building in the same job. Here is why insurance matters:
What comes off a roof lands on someone: A slipped slate, a dropped tool or a sheet caught by wind can injure a passer-by or wreck a car below. Public Liability takes care of your defence costs and the compensation due.
The property involved in your work can be damaged: Roofing can expose property to accidental damage. Included cover for property in your care applies to property you work on, handle or process, property unavoidably involved in your work, or property deliberately used as an aid, subject to the policy terms. Limits are €25,000 per claim for a one-person business or €50,000 if more than one person works in the business, and twice those amounts per year.
Putting other trades' work back costs money: Optional additional-work cover can pay qualifying third-party access and reinstatement costs needed to reach and repair a defect. It does not pay to redo your own roof work or replace your own materials. Limits are €25,000 per claim for a one-person business or €50,000 otherwise, twice those amounts per insurance year, with €500 additional excess on top of your chosen excess.

What is Public Liability insurance?
If a third party, like a client or a member of the public, holds you responsible for an injury or for damage to their property, Public Liability takes care of your defence costs and any compensation due.
What does it cover?
Injury or property damage caused to others in the course of your roofing work. Your cover limit is €2.5 million per claim and €5 million per insurance year. Damage to property in your care, custody or control is included, up to €25,000 per claim for a one-person business or €50,000 if more than one person works in the business, and twice those amounts per year.
What can you add?
Employers' Liability, €13 million per claim, if you employ anyone.
Cost of additional work, for qualifying third-party access and reinstatement costs needed to reach and repair a defect. It does not pay to repair or replace your own work or materials. Limits are €25,000 per claim for a one-person business or €50,000 if more than one person works in the business, twice those amounts per year, with €500 additional excess on top of your chosen excess.
Cover that fits your trade
You describe your work fully at sign-up, and your cover matches what you actually do: installing roof structures, laying roof tiles, laying tar paper, installing skylights and installing a dormer.
Work you have to declare
Some of what you tell us changes your premium, and some answers mean you will not be eligible for an online quote. As a roofer you are asked about:
Fire-hazardous work: any work involving heat, such as bitumen burning, flame soldering, welding, cutting, grinding, paint stripping, and work with hot air such as blow-drying. Torch work on flat roofs sits squarely in this, so answer it accurately. Cover for fire-hazardous work requires your activities to be declared and accepted and the relevant endorsement to be shown in your policy schedule. The remaining policy terms, exclusions, limits and excess still apply.
Subcontractors: whether more than 50% of your revenue comes from subcontractors, meaning people you hire to carry out work on your behalf. If it does and your annual revenue is above €500,000, we cannot quote you online. Contact us to discuss whether any cover is available; acceptance is not guaranteed.
Experience: whether you have at least 3 years of experience with the activities your company carries out. You are only asked this if your business has been trading for less than 36 months, and your answer affects your premium.
Revenue from outside the European Union: whether more than 50% of your revenue comes from outside the European Union. If it does, we cannot quote you online. Contact us to discuss whether any cover is available; acceptance is not guaranteed.
How much can your business turn over?
This cover is written for roofing businesses turning over up to €2,500,000 a year, with up to 30 people. That revenue ceiling is lower than for most trades we cover. Above it, we cannot quote you online.
Is it mandatory?
Public Liability is not required by law in Ireland. In practice, main contractors, housing bodies, letting agents and local authorities ask for proof of cover before they let you on site. Cover starts from €21.84 per month.
What does our insurance cover for roofers?
Cover for roofers is built around Public Liability on the construction rating, with optional covers you can add to match your situation.
Public Liability: Protects you if a client or another third party suffers an injury, or their property is damaged, in the course of your roofing work. It takes care of your defence costs and any compensation due. Your cover limit is €2.5 million per claim and €5 million per insurance year.
Third-party objects and sites: Included as standard on this trade. Covers damage to property belonging to others that you actually work on, handle or process, that is unavoidably involved in your work, or that you deliberately use as an aid. It does not automatically include every part of a building simply because you work there. Limits are €25,000 per claim for a one-person business or €50,000 otherwise, and twice those amounts per insurance year.
Employers' Liability (optional): If you employ staff, this covers your liability as an employer, with a limit of €13 million per claim.
Cost of additional work (optional): Can pay qualifying third-party access and reinstatement costs needed to reach and repair a defect. It does not pay to repair or replace your own work or materials. Limits are €25,000 per claim for a one-person business or €50,000 otherwise, twice those amounts per insurance year, with €500 additional excess on top of your chosen excess.
What's covered
Trade in related construction goods and materials
Application of plaster on walls and/or ceilings
Construction, installation, modification, maintenance and repair of wooden floors, walls, ceilings, stairs, doors and windows
Execution of business trips and company events
Participation in seminars or training courses
Optional: Employers' Liability if you employ anyone (€13 million per claim)
Optional: additional-work cover for qualifying third-party access and reinstatement costs, not repair or replacement of your own work or materials (€25,000 per claim for a one-person business or €50,000 if more than one person works in the business; twice those amounts per year; €500 additional excess on top of your chosen excess)
Activities outside the EU, Iceland, Liechtenstein, Norway, Switzerland, and the United Kingdom are not covered.
Motor liability apart from tools of trade used on a contract site
Advice, design or specification provided separately for a fee or under a separate contract
Cyber liability and failure of systems
Claims or circumstances you already knew about when the cover started
Key site exclusions include industrial and agricultural buildings and public infrastructure. Other policy exclusions apply; see the policy wording.
Cover and exclusions shown are indicative and non-contractual. Only the terms of your policy apply.
Claim examples for roofers
You strip a pitched roof in Limerick and rain gets in overnight before the felt is back on, damaging ceilings and plasterwork below. If you are legally liable, cover depends on the circumstances and the property's relationship to your work. Limits for property in your care may apply to property worked on or unavoidably involved; other accidental property damage may fall under Public Liability, subject to the policy terms, exclusions and excess.
A slate works loose weeks after a repair, comes off in a gale and lands on a parked car. The owner holds you responsible. Public Liability takes care of your defence costs and the compensation due.
While torching felt on a flat roof you scorch the fascia and part of the roof void. Because you declared fire-hazardous work when you took out cover, the claim is handled.
You strip a pitched roof in Limerick and rain gets in overnight before the felt is back on, damaging ceilings and plasterwork below. If you are legally liable, cover depends on the circumstances and the property's relationship to your work. Limits for property in your care may apply to property worked on or unavoidably involved; other accidental property damage may fall under Public Liability, subject to the policy terms, exclusions and excess.
A slate works loose weeks after a repair, comes off in a gale and lands on a parked car. The owner holds you responsible. Public Liability takes care of your defence costs and the compensation due.
While torching felt on a flat roof you scorch the fascia and part of the roof void. Because you declared fire-hazardous work when you took out cover, the claim is handled.
Examples are for illustrative purposes only. Compensation depends on the exact circumstances of the claim. No rights can be derived from these examples.
Your business insurance with Insify SmartGuide
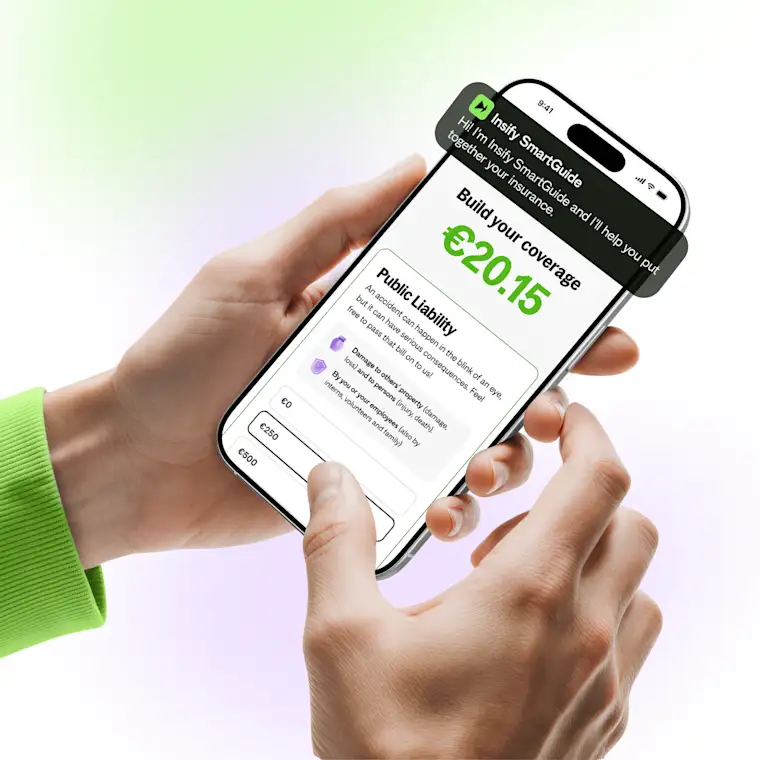
Taking out insurance can be quick. Making sure you have the right cover is another matter. With Insify SmartGuide, you don't sign a contract blindly. You ask all your questions, and get clear, immediate and personalised answers, before you take out a policy.
Are you covered if you accidentally damage a client's equipment while working?
What excess should you choose?
Are you protected in the event of a dispute with a client?
Insify SmartGuide guides you step by step to understand what's covered, what isn't, and why. In just a few clicks, you build insurance that's truly tailored to your business, with complete confidence. Try Insify SmartGuide. Understand your insurance before you need it.
How to choose the right insurance as a roofer?
Criteria to compare:
The cover offered: Check the policy matches how you actually work; height, weather, the building you are standing on, and torch or hot-air work if you do it. Make sure each one is covered.
The price: Compare premiums, but an attractive price can hide exclusions that matter on a roof.
The excess: Know what stays at your own expense when a claim happens.
The exclusions: Watch for the ones specific to the trade; work you have not declared, specialist installations, and marketing that promises guaranteed results.
The service: Check how you get answers before you buy, not after a claim. An insurer that understands roofing will ask about the work you take on at height and in heat.
Mistakes to avoid: Do not settle for a generic policy that ignores what happens when a roof is open to the weather. To secure your business today, discover our Public Liability insurance.
More than 50,000 entrepreneurs trust us
When I had to make a claim, I was amazed how quickly and efficiently it was handled. Within a few days I had a resolution.
Very friendly, quick and thorough. It gives me real confidence in taking out the cover. The company feels genuinely transparent, exactly what I look for. You don't find that often.
Very friendly, quick and thorough. It gives me real confidence in taking out the cover. The company feels genuinely transparent, exactly what I look for. You don't find that often.
When I had to make a claim, I was amazed how quickly and efficiently it was handled. Within a few days I had a resolution.
The cover itself was sorted quickly, and when I later needed support I got that fast too.
Very friendly, quick and thorough. It gives me real confidence in taking out the cover. The company feels genuinely transparent, exactly what I look for. You don't find that often.
When I had to make a claim, I was amazed how quickly and efficiently it was handled. Within a few days I had a resolution.
The cover itself was sorted quickly, and when I later needed support I got that fast too.
Insurance guides for construction and trades
 InsuranceWhat does it cost a tradesman when a job goes wrong? Five years of real claims
A cable you could not see, a joint that was not quite tight, a ladder that slides. Real figures on how often things go wrong on the job in your trade, and what the bill looks like.
 InsuranceWhat is public liability insurance, and what does it cover?
Someone else gets hurt, or their property gets damaged, and they hold you responsible. Here is what sits inside it, what sits outside, and how the limit you pick changes the policy.
InsuranceWhat does it cost a tradesman when a job goes wrong? Five years of real claimsA cable you could not see, a joint that was not quite tight, a ladder that slides. Real figures on how often things go wrong on the job in your trade, and what the bill looks like.
InsuranceWhat is public liability insurance, and what does it cover?Someone else gets hurt, or their property gets damaged, and they hold you responsible. Here is what sits inside it, what sits outside, and how the limit you pick changes the policy.
Answers to your questions about our insurance for roofers
The price depends on your turnover, the work you do, how many people work in your business and the excess you choose. At Insify, Public Liability for a roofer starts from €21.84 per month. Roofing is rated on our construction basis, which is why it starts higher than trades that carry less risk of injury and property damage. A personalised quote takes a few minutes online, and you can adjust the excess to see how it moves your premium.
Public Liability is not required by law in Ireland. In practice you will be asked for it constantly. Main contractors will not let you on site without a certificate, housing bodies and letting agents ask before handing over keys, and local authorities and public tenders set their own minimum limits. Having cover in place also means you are not personally exposed if someone claims against you after an injury.
Public Liability covers injury and damage to other people and their property, not the cost of redoing your own work. Optional additional-work cover can pay qualifying third-party access and reinstatement costs needed to reach and repair a defect. It does not pay to repair or replace your own work or materials. Limits are €25,000 per claim for a one-person business or €50,000 if more than one person works in the business, twice those amounts per year, with €500 additional excess on top of your chosen excess. Injury or other property damage caused by a defect may fall under Public Liability, subject to the policy terms.
Rain damage can be covered if you are legally liable, depending on the circumstances and the policy terms. Included cover for property in your care applies to property you work on, handle or process, property unavoidably involved in your work, or property deliberately used as an aid. It does not automatically include the whole building. The limit is €25,000 per claim for a one-person business or €50,000 if more than one person works in the business, and twice those amounts per insurance year. Other accidental property damage may fall under the main Public Liability limit. Your own tools, materials and van are not covered by this liability policy.
Yes. Fire-hazardous work is one of the questions we ask, and it covers bitumen burning, flame soldering, welding, cutting, grinding, paint stripping and work with hot air. Torching felt on a flat roof is exactly that. Your answer affects your premium rather than removing cover, so answer it accurately: a claim arising from work you did not declare is a problem you do not want to find out about after a fire.
Roofing is rated on our construction basis, and that comes with a single cover limit of €2.5 million per claim and €5 million per insurance year. Trades on our general rating can choose between €1.25 million, €2.5 million and €6.5 million, but that choice is not available here. If a contract or a tender asks you for more than €2.5 million, tell us before you buy so we can check whether we can cover the work.
Yes, and it is lower for roofing than for most trades. This cover is written for roofing businesses turning over up to €2,500,000 a year, with up to 30 people. Most of the trades we cover online can turn over 4 times that. If you are above the ceiling, we cannot quote you online, and it is worth telling us early rather than at the end of a quote.
The excess is the part of a claim you pay yourself. If a claim settles at €4,000 and your excess is €500, you pay €500 and Insify pays €3,500. The options are €0, €250, €500, €1,000 and €2,500, with €0 and €250 available up to €500,000 annual revenue; above that the minimum is €500. A higher excess usually lowers your premium but means more out of pocket when a claim happens. The optional cost of additional work cover carries its own €500 excess.
Yes. Employers' Liability is a separate optional cover with a limit of €13 million per claim, and it is not part of your policy unless you add it. Employers' Liability is not compulsory in Ireland, unlike the United Kingdom, but you are still liable as an employer. The limit for property in your care is €25,000 per claim for a one-person business or €50,000 if more than one person works in the business. The count includes working owners and partners as well as employees and other people working in the business. These limits are doubled per insurance year, so tell us when the number of people in your business changes.