Courier insurance in Ireland
Courier work brings different insurance needs. Insify provides public liability for covered claims arising from your delivery work, not motor insurance or hire-and-reward motor cover. If you use a motor vehicle for paid deliveries, ask your motor insurer to confirm that use is covered.
Public Liability with cover limits up to €6.5 million.
Goods in your custody and care included up to €5,000 per claim, subject to policy terms.
Learn more about our Public Liability cover


Business insurance, done differently.

Fully online business insurance in Ireland.

A few questions and you're covered.

No lock-in, no long contracts.

Up to €5,000 per claim for covered damage to goods in your care.
Why take out business insurance as a courier?
Courier work can cause injury or damage during collections, drop-offs and handovers. Public liability addresses these business liabilities; it does not replace motor insurance.
Someone gets hurt: a parcel left across a doorstep or a sack truck across a footpath can cause a trip.
You damage a client's property: a cabinet clipped at a delivery or a floor damaged in a reception.
Goods in your care get damaged: a consignment dropped at handover can lead to a claim.
Clients ask for cover: check the insurance requirements in your delivery contracts.
Public liability can cover compensation and defence costs for covered claims. Goods in your custody and care has its own €5,000 per-claim and €10,000 annual limit. Cover depends on your declared activities and policy terms.
What is Public Liability insurance for couriers?
Public liability covers your legal liability for covered injury to other people or damage to their property arising from your declared work. For couriers, this can include collections, drop-offs and handovers. It does not replace motor insurance.
How it works: declare your activities and choose a cover limit and excess. Covered compensation and defence costs are subject to your policy terms.
What it covers: third-party injury, property damage and legal defence costs. Courier cover for property in your care has a separate €5,000 per-claim and €10,000 annual limit.
What it is not: this is not motor insurance or hire-and-reward motor cover, and is not a replacement for separate goods-in-transit insurance.
Contract requirements: check whether your clients or delivery platforms require public liability and what cover limit they specify.
Who can apply: sole traders and delivery businesses with supported declared activities, subject to underwriting eligibility. Tell us about every service you provide.
What does our insurance cover for couriers?
Cover is based on the activities you declare and the terms of your policy.
Public liability: choose €1.25 million, €2.5 million or €6.5 million per claim, with twice that amount per insurance year.
Excess: options from €0 to €2,500 for turnover up to €500,000, and from €500 to €2,500 above that turnover. Check the excess shown in your quote and schedule.
Goods in your custody and care: included as standard for supported courier activities, up to €5,000 per claim and €10,000 per insurance year. Loss or disappearance is not insured under this cover.
Employers' liability: optional cover for qualifying employee claims, with €13 million per claim and €13 million per insurance year.
Activities: food courier, non-food courier, newspaper delivery and parcel delivery are supported activities. Declare the services you actually provide so eligibility can be checked.
Business eligibility: turnover up to €10 million and up to 30 people, subject to underwriting requirements.
What we cover and what we don't
This summary is indicative and non-contractual. Cover is subject to your declared activities, policy terms, limits and exclusions. Only the terms of your policy apply.
Public liability for covered third-party injury or property-damage claims arising from your declared courier work, plus covered defence costs.
Goods in your care: qualifying damage up to €5,000 per claim and €10,000 per insurance year. Included for supported courier activities.
Optional employers' liability: qualifying employee claims up to €13 million per claim and per insurance year.
Declared insured activities can include business trips, use of land or premises, road transport and transfer of goods, subject to policy terms.
Food, non-food, newspaper and parcel delivery are supported activities. Declare your actual services when applying.
Damage caused with or by a motor vehicle you drive or use. This does not apply to damage caused by items being loaded onto or unloaded from it. Each vehicle needs its own motor insurance.
Loss or disappearance of goods in your care. Cover for property in your care applies to qualifying damage, up to €5,000 per claim and €10,000 per insurance year; it is not separate goods-in-transit insurance.
Moving services are excluded for non-food courier and parcel-delivery activities. Declare any removals work rather than assuming cover.
Transport by water, rail or air, and transport of animals or livestock.
Private use of a company bicycle and/or storing it at your home. Declare bicycle, e-bike or e-cargo-bike use and check your policy terms.
Cover and exclusions shown are indicative and non-contractual. Only the terms of your policy apply.
Some examples, for illustration
A customer in Limerick tripped over a parcel left across their doorstep, fractured an ankle and claimed for treatment and lost earnings.
A sack truck clipped a glass display cabinet in a Cork pharmacy during a delivery. The owner claimed for the cabinet and the stock inside it.
A consignment of electronic parts was dropped at handover and written off. The retailer claimed for the value of the goods in the courier's care.
A customer in Limerick tripped over a parcel left across their doorstep, fractured an ankle and claimed for treatment and lost earnings.
A sack truck clipped a glass display cabinet in a Cork pharmacy during a delivery. The owner claimed for the cabinet and the stock inside it.
A consignment of electronic parts was dropped at handover and written off. The retailer claimed for the value of the goods in the courier's care.
Examples are for illustrative purposes only. Compensation depends on the exact circumstances of the claim. No rights can be derived from these examples.
Your business insurance with Insify SmartGuide
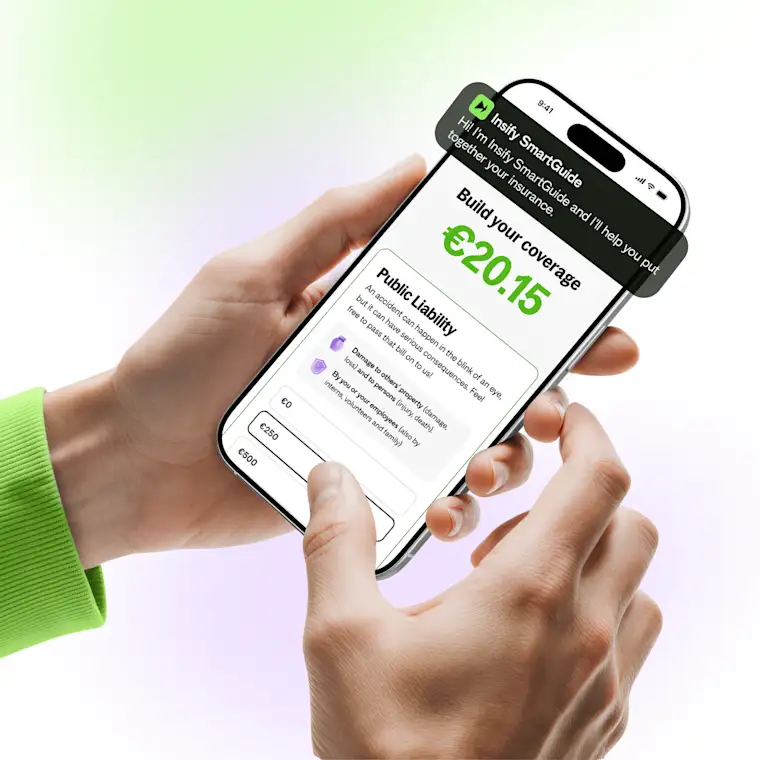
Taking out insurance can be quick. Making sure you have the right cover is another matter. With Insify SmartGuide, you don't sign a contract blindly. You ask all your questions, and get clear, immediate and personalised answers, before you take out a policy.
Does this cover my van or hire and reward?
Are the parcels I carry covered if I drop one?
Do I need this if I deliver for a platform?
Insify SmartGuide guides you step by step to understand what's covered, what isn't, and why. In just a few clicks, you build insurance that's truly tailored to your business, with complete confidence. Try Insify SmartGuide. Understand your insurance before you need it.
How to choose the right insurance as a courier
Compare the cover you need for your vehicle, your liability and the goods you handle. Check your contracts and policy terms, not just the premium.
Motor and paid deliveries: ask your motor insurer to confirm that your vehicle policy covers your courier work, including hire and reward where required. Insify does not provide motor cover.
Public liability: check the cover limit required by your clients and the activities covered, including collections, handovers and work on client premises.
Goods in your care and goods in transit: Insify's cover for property in your care has a €5,000 per-claim limit and does not insure loss or disappearance. Separate goods-in-transit policies have their own insured risks, limits and exclusions. Check what your contract requires.
People working for you: consider the employers' liability add-on and tell us about employees and others working under your direction. Eligibility depends on how they work for you.
Declare every activity: tell us about food, parcels, newspapers and any other services. Removals and other activities may be excluded. Check your quote and policy schedule before relying on cover.
Learn more about our Public Liability insurance
More than 50,000 entrepreneurs trust us
When I had to make a claim, I was amazed how quickly and efficiently it was handled. Within a few days I had a resolution.
Very friendly, quick and thorough. It gives me real confidence in taking out the cover. The company feels genuinely transparent, exactly what I look for. You don't find that often.
Very friendly, quick and thorough. It gives me real confidence in taking out the cover. The company feels genuinely transparent, exactly what I look for. You don't find that often.
When I had to make a claim, I was amazed how quickly and efficiently it was handled. Within a few days I had a resolution.
The cover itself was sorted quickly, and when I later needed support I got that fast too.
Very friendly, quick and thorough. It gives me real confidence in taking out the cover. The company feels genuinely transparent, exactly what I look for. You don't find that often.
When I had to make a claim, I was amazed how quickly and efficiently it was handled. Within a few days I had a resolution.
The cover itself was sorted quickly, and when I later needed support I got that fast too.
Answers to your questions about our insurance for couriers
Your public liability price depends on your declared activities, turnover, cover limit and excess. Get a quote to see the price for your courier business before you buy. Insify public liability is not motor or hire-and-reward insurance. Arrange any motor or separate goods-in-transit cover you need with an appropriate provider.
Consider the risks from your delivery work, your vehicle and the goods you carry separately. Insify public liability covers qualifying claims for injury to other people or damage to their property, with limited cover for property in your care for entrusted goods. It is not motor or hire-and-reward insurance. Ask your motor insurer to confirm that your cover permits paid deliveries, and check your client or platform contract for public liability and goods-in-transit requirements.
No. Damage caused with or by your van is generally excluded from public liability, so it needs your motor insurance. Damage caused by goods you are loading onto or unloading from it can still fall under public liability, subject to the policy terms.
Liability for qualifying damage to goods in your custody and care is included as standard, up to €5,000 per claim and €10,000 per insurance year. Loss or disappearance is excluded. This does not insure every consignment for its full value. If your contract requires goods-in-transit or cargo insurance, arrange that separately.
Yes. Employers' liability is optional and provides up to €13 million per claim and per insurance year for your legal liability if an employee is injured or becomes ill because of their work. Check the cover required by your delivery contracts and public tenders.
Insify offers public liability limits of €1.25 million, €2.5 million or €6.5 million per claim, with twice the chosen amount per insurance year. Check both your business risks and the minimum limits required by your contracts. A default quote option is not a recommendation that the amount is sufficient for your business. Custody-and-care and employers' liability cover have their own limits.
The excess is the amount you pay towards an insured claim. For annual turnover up to €500,000, the available public liability excesses are €0, €250, €500, €1,000 or €2,500. Above €500,000, the options are €500, €1,000 or €2,500. Check your quote and policy schedule for the applicable excess and any specific terms.
Declare every service you provide, including food delivery, non-food courier work, parcel delivery and newspaper delivery. These are separate supported activities, and your quote and policy must reflect your actual work. Tell us about any removals or other transport work too: moving services are excluded for non-food couriers and parcel delivery, and transport by water, rail or air and of animals or livestock is excluded. Check the activities and terms on your policy before starting work.