Employers' liability insurance in Ireland
Why add employers' liability cover?
Because one workplace injury claim can cost more than your business earns in a year, and without cover you pay it yourself.
Who it is for: businesses with employees or other people who may count as employees under the policy, including some interns, volunteers, family members and subcontractors. Tell us how people work for you so your quote reflects your business.
What it does: it responds when an employee is injured or made ill by their work and holds you responsible, covering the compensation and your defence costs.
Why it matters in Ireland: Section 8 of the Safety, Health and Welfare at Work Act 2005 requires employers to ensure employees' safety, health and welfare at work, so far as reasonably practicable.
How you get it: it is not a separate policy. You add it to your Public Liability cover when you apply, so there is one policy, one price and one place to claim.

Business insurance, done differently.

Fully online business insurance in Ireland.

A few questions and you're covered.

No lock-in, no long contracts.

Employers' liability: €13 million per claim and per insurance year.
What is Employers' Liability insurance?
Employers' liability insurance covers claims from the people who work for you. Public liability covers claims from clients and the public. Same accident, different claimant: a customer who slips in your shop is a public liability claim, and a staff member who slips is an employers' liability claim.
If there's a chance a client could hold you liable for purely financial loss, it's worth also considering Professional Indemnity cover.
What does it cover?
You have a limit of €13 million per claim and €13 million per insurance year. Applicable defence costs are included within that limit. The work must fall within your insured business activities, and the policy's conditions and exclusions apply.
How does it work?
You choose Public Liability, tick employers' liability and answer a few questions about your activities, turnover and the number of people working for you. If an employee later claims against you, you report it to us and we handle the claim and your defence. Additional allowances for employees are paid inside the €13 million limit, not on top of it.
Who needs Employers' Liability in Ireland?
You need it if anyone works under your direction, even one person or part-time. You probably don't if you work alone and only use independent subcontractors with their own insurance.
One full-time employee: Yes, recommended. One employee can bring a claim like any larger team.
Part-time, casual or seasonal staff, apprentices: Yes. Part-time status does not reduce your duty of care.
Labour-only subcontractors (your tools, your direction): Yes. They are often treated as employees, so a claim from one falls to employers' liability. Tell us when you apply.
Independent subcontractors with their own insurance: Usually not for them. Ask to see their policy. Public liability still matters for you.
Sole trader with no staff: Usually not. Employers' liability covers your liability to employees and other subordinates; it is not personal accident cover for you as the sole-trader policyholder. Look at public liability instead.
Co-directors and family members who work in the business: Depends on how they're engaged.
What counts is how someone actually works for you, not what the contract calls them. Citizens Information explains how employment status is decided in Ireland.
Is Employers' Liability insurance mandatory in Ireland?
Purchasing employers' liability is not compulsory in Ireland, but clients and site operators may require it. Check any insurance requirement in your contracts.
How much does employers' liability cover cost?
How it is priced: employers' liability is added to your Public Liability policy, so you pay one premium. Public liability starts from €7.55 per month. The employers' liability add-on is priced on your business when you apply.
What moves the price: your activities, turnover and the number of people working for you.
Cover amount: €13 million per claim, and €13 million per insurance year. Unlike public liability, the yearly limit is not double the per-claim limit, it is the same figure.
Which cover do you need?
Most businesses are exposed to both. One covers injury and damage, the other financial loss from your work. You can combine them in one Insify policy. Cover limits, excess and exclusions apply. See the policy wording.
Public Liability insurance
Covers claims when your work injures someone or damages something that belongs to them. For example, someone trips over your equipment, or you damage a floor while working at a client's premises.
- Choose your cover: from €1.25 million up to €6.5 million per claim, and up to twice that per insurance year
- Excess from €0, depending on your turnover
- Staff? Add optional Employers' Liability with €13 million cover per claim
- Most relevant when your work brings you into contact with clients, the public, their premises or their belongings
Professional Indemnity insurance
Covers purely financial loss a client suffers through a professional mistake, oversight or wrong advice, with no injury or property damage involved. Think of work a client claims was unfit for purpose and cost them money.
- Choose your cover: from €125,000 up to €1.25 million per claim, and up to twice that per insurance year
- Excess from €0, depending on your turnover
- Most relevant when clients pay you for advice, programmes and plans
What's covered
Compensation and defence costs when an employee is injured or made ill by their work and holds you liable.
Cover of €13 million per claim, and €13 million per insurance year. Additional allowances for employees are paid inside this limit, not on top of it.
Available as an option on every activity Insify insures in Ireland.
Territorial scope follows your public liability policy: the EU plus Iceland, Liechtenstein, Norway, Switzerland and the UK, with business trips worldwide, excluding the USA and Canada.
Damage you cause intentionally.
Employers' liability covers your liability to employees and other subordinates; it is not personal accident cover for you as the sole-trader policyholder.
Very large risks, or locations that carry major risks.
Gradual or slow-acting environmental damage. Only sudden, accidental pollution is covered.
Claims caused by a cyber attack, hack or social engineering.
Cover and exclusions shown are indicative and non-contractual. Only the terms of your policy apply.
Some examples
A kitchen porter in your Limerick restaurant slips on a wet floor, fractures a wrist and brings a claim for lost earnings and treatment.
A general operative on your site in Cork falls from a low platform and is out of work for months, and the claim covers compensation and your legal defence.
A long-serving warehouse employee in Dublin develops a back injury they attribute to repeated manual handling, and brings a claim against your business.
A kitchen porter in your Limerick restaurant slips on a wet floor, fractures a wrist and brings a claim for lost earnings and treatment.
A general operative on your site in Cork falls from a low platform and is out of work for months, and the claim covers compensation and your legal defence.
A long-serving warehouse employee in Dublin develops a back injury they attribute to repeated manual handling, and brings a claim against your business.
Examples are for illustrative purposes only. Compensation depends on the exact circumstances of the claim. No rights can be derived from these examples.
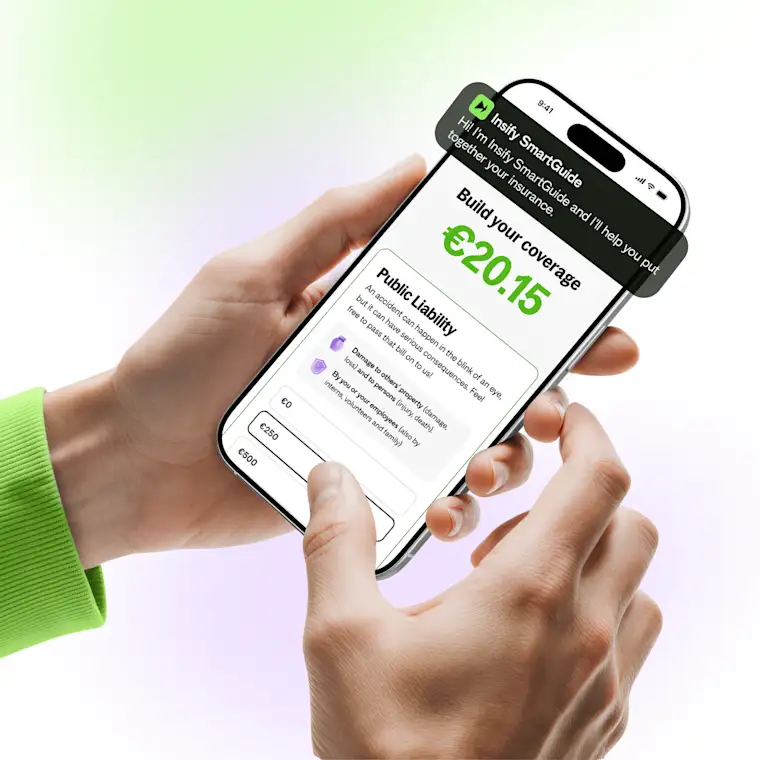
Your business insurance with Insify SmartGuide
Taking out insurance can be quick. Making sure you have the right cover is another matter. With Insify SmartGuide, you don't sign a contract blindly. You ask all your questions, and get clear, immediate and personalised answers, before you take out a policy.
Do I need employers' liability if I only use subcontractors?
Is my part-time staff member covered?
What happens if an employee gets injured on a client's site?
Insify SmartGuide guides you step by step to understand what's covered, what isn't, and why. In just a few clicks, you build insurance that's truly tailored to your business, with complete confidence. Try Insify SmartGuide. Understand your insurance before you need it.
More than 50,000 entrepreneurs trust us
When I had to make a claim, I was amazed how quickly and efficiently it was handled. Within a few days I had a resolution.
Very friendly, quick and thorough. It gives me real confidence in taking out the cover. The company feels genuinely transparent, exactly what I look for. You don't find that often.
Very friendly, quick and thorough. It gives me real confidence in taking out the cover. The company feels genuinely transparent, exactly what I look for. You don't find that often.
When I had to make a claim, I was amazed how quickly and efficiently it was handled. Within a few days I had a resolution.
The cover itself was sorted quickly, and when I later needed support I got that fast too.
Very friendly, quick and thorough. It gives me real confidence in taking out the cover. The company feels genuinely transparent, exactly what I look for. You don't find that often.
When I had to make a claim, I was amazed how quickly and efficiently it was handled. Within a few days I had a resolution.
The cover itself was sorted quickly, and when I later needed support I got that fast too.
Questions and answers about employers' liability
No. Ireland has no law requiring employers' liability insurance. Under section 8 of the Safety, Health and Welfare at Work Act 2005, employers must ensure employees' safety, health and welfare at work, so far as reasonably practicable. You also owe employees a duty of care at common law. If someone is injured and you are held liable, you pay the compensation and legal costs yourself unless you're insured. Many main contractors and public bodies also ask for proof of cover.
It isn't legally required, but one employee can bring a claim just like a large team. The duty of care applies from your first employee, including part-time and casual staff.
It depends on how they work for you. A genuinely independent subcontractor runs their own business and carries their own insurance, so ask to see it. Labour-only subcontractors who work under your direction and use your equipment are often treated as employees, and a claim from one would fall to employers' liability. If you use labour-only people, tell us when you apply.
No. Employers' liability is an optional add-on to Insify's Public Liability insurance, not a separate policy. That suits most small employers, because the same working day creates both risks, and one policy covers both.
€13 million per claim and €13 million in total per insurance year, including applicable defence costs. This limit is fixed. Check it against any requirement in your contracts.
Compensation you're legally liable for when someone working for you is injured or made ill by their work, plus the cost of defending the claim. Additional allowances for employees are paid inside the €13 million limit.
Usually not. Employers' liability covers your liability to employees and other subordinates; it is not personal accident cover for you as the sole-trader policyholder. Public liability is the cover most sole traders need. If you start hiring, even one helper, add employers' liability at that point.
At Insify it's priced together with your Public Liability, which starts from €7.55 per month. The price depends on your trade, turnover and the number of people working for you.
Employers' liability insurance in Ireland covers claims from the people who work for you. Public liability covers claims from clients and the public. It isn't compulsory, but employers still carry duties under the Safety, Health and Welfare at Work Act 2005, and an uninsured workplace injury claim is paid from your own pocket. You likely need it if you have even one employee, part-time staff or labour-only subcontractors. You probably don't if you work alone and only hire independent subcontractors. Insify offers employers' liability as an optional add-on to Public Liability, with €13 million cover per claim and per insurance year on every activity we insure. To add it, take out Public Liability from €7.55 per month and select employers' liability when you apply. If your clients could also claim against you for financial loss caused by your professional work, consider Professional Indemnity from €10.80 per month alongside it, where your activity qualifies for that cover.
Examples are for illustrative purposes only. Compensation depends on the exact circumstances of the claim. No rights can be derived from these examples.