Landscaping insurance
You build and look after outdoor spaces that belong to someone else. Public liability answers when your work injures someone or damages property that isn't yours.
For landscape construction, garden and grounds maintenance, and planting, with tree work covered up to 3 metres.
Public liability from €21.84 a month, with €2.5 million of cover per claim.
Online quote in minutes, no long-term commitment, cancel any day.


Business insurance, done differently.

Fully online business insurance in Ireland.

Answer a few questions for your quote. Cover can start tomorrow.

No lock-in, no long contracts.

Excess from €0, with €2.5 million of cover per claim and €5 million per year.
Why landscape businesses take out public liability
Landscaping puts diggers, compactors, saws and mowers to work on ground your client owns, often next to their house, their car and their neighbours. That is where claims come from.
You work in public. A stone flies off your strimmer and hits a passer-by, or a branch you cut falls on a parked car. Your policy pays up to €2.5 million.
You damage what you're working on. You crack the paving you're laying, or cut a pipe while digging. Your policy pays up to €25,000, or €50,000 if more than one person works in your business. Damage to anything else, like the client's house or their neighbour's car, is covered up to €2.5 million.
Someone else's work has to come up because of your mistake. A drain you laid leaks under another contractor's paving. With the optional Faulty craftsmanship add-on, your policy pays to lift and relay their paving. It doesn't pay to fix your drain.
What is public liability insurance?
Public liability answers the claim when somebody outside your business is hurt by your work, or something of theirs is damaged by it. It pays what you are legally liable for, and the cost of defending you.
What does it cover?
Your legal liability for injury to third parties or damage to their property arising from insured gardening work. The limit is €2.5 million per claim and €5 million per insurance year. Property you work on or necessarily involve in the job is subject to the limit for property in your care: €25,000 per claim for a one-person business or €50,000 if more than one person works in the business. Other accidental third-party damage may fall under the main limit. Employee claims need Employers' Liability cover.
What can you add?
Employers' Liability at €13 million a claim, which you can add if you employ staff or seasonal help.
Cost of additional work for qualifying third-party access and reinstatement costs, with limits of €25,000 per claim for a one-person business or €50,000 if more than one person works in the business. A €500 additional excess applies on top of your chosen excess. Repairing your own work or materials is not covered.
Cover that fits how you work
Set out everything your business takes on when you sign up, and the policy follows it: laying out and maintaining gardens and other green spaces, plus the materials you buy in for a job and pass on to the client. Tree work is included up to a height of 3 metres. Trimming or felling anything taller is not.
Work you have to declare
Some answers affect your price or the work your policy can cover. Others mean we cannot quote online. Describe your work accurately and answer the sign-up questions fully:
Fire-hazardous work. This means any work involving heating, such as welding, cutting, grinding, flame soldering, paint stripping, bitumen burning, and work with hot air such as blow-drying. The question is about the operation, not the trade, so describe any of this work accurately. Cover requires it to be accepted and included by the relevant endorsement in your policy schedule. Other policy terms still apply.
Subcontractors. Tell us if more than 50% of your revenue comes from subcontractors, meaning people you hire to carry out work on your behalf. Above €500,000 of revenue, that combination means we cannot quote online. Contact us to discuss your options before bidding for a grounds-maintenance contract.
Where your revenue comes from. If more than 50% of your revenue comes from outside the European Union, we cannot quote online. Contact us to discuss your options.
Your experience. If your business has been trading for less than 36 months, we ask whether you have at least 3 years of experience with the activities your company carries out. It affects your price.
Is it mandatory?
Public liability is not required by law in Ireland. In practice, the people who hire you ask for it first: main contractors and developers before they let you on site, management companies before you maintain estate grounds, and local authorities and public tenders, which set their own minimum limits. Public liability starts from €21.84 a month.
What our landscaping insurance covers
Landscaping is rated as construction work, so public liability is the base and you add to it depending on how your business runs.
Public liability. Answers a claim when a client, a neighbour or a passer-by is injured, or something of theirs is damaged, because of your landscaping work. It pays the compensation you owe and the cost of defending you, to €2.5 million a claim and €5 million an insurance year.
Third-party objects and sites: Included as standard for qualifying damage to property you work on, handle or necessarily involve in the job, or deliberately use as an aid. The limit is €25,000 per claim for a one-person business or €50,000 if more than one person works in the business. The property's relationship to your work determines the limit, not simply where it is.
Tree work above 3 metres is not covered. Trimming or felling a tree taller than 3 metres is outside this cover, in a garden, on a boundary or on estate grounds. Work on playgrounds is outside it too. If either is part of what you do, tell us before you buy.
Employers' Liability (optional): You can add this if you employ staff or seasonal help. €13 million per claim.
Faulty craftsmanship (optional). If a mistake in your work means another contractor's work has to be taken apart to reach it, this add-on pays to take it apart and put it back. It does not pay to repair or replace your own work or materials. Covered up to €25,000 a claim, or €50,000 a claim if more than one person works in your business, with its own €500 excess.
What's covered
Layout and maintenance of gardens and other green spaces
Trade in related construction goods and materials
Use of land, buildings or premises for the insured activity
Execution of business trips and company events
Participation in seminars or training courses
Optional: Employers' Liability if you employ anyone (€13 million per claim)
Optional: additional-work cover for qualifying third-party access and reinstatement costs, excluding repair or replacement of your own work (€25,000 per claim for a one-person business or €50,000 if more than one person works in the business; €500 additional excess)
Trimming or felling trees more than 3 metres tall
Work on playgrounds
Activities outside the EU, Iceland, Liechtenstein, Norway, Switzerland, and the United Kingdom are not covered.
Claims, and circumstances that could give rise to a claim, that you or an insured person is aware of on the date the cover starts
Key site exclusions also include industrial and agricultural premises and public infrastructure. This is a summary; other policy exclusions apply. See the full policy wording.
Cover and exclusions shown are indicative and non-contractual. Only the terms of your policy apply.
Claim examples for landscape businesses
Your crew is strimming a boundary and a stone goes through the neighbour's conservatory panel and into their parked car. Public liability covers that.
Your mini digger cuts a buried water pipe and the client's ground floor floods. Your policy covers damage your work causes to other people's property, up to the limits on your policy.
You're cutting back a hedge along a footpath and a branch falls on a passer-by, injuring their shoulder. Your public liability pays their claim.
Your crew is strimming a boundary and a stone goes through the neighbour's conservatory panel and into their parked car. Public liability covers that.
Your mini digger cuts a buried water pipe and the client's ground floor floods. Your policy covers damage your work causes to other people's property, up to the limits on your policy.
You're cutting back a hedge along a footpath and a branch falls on a passer-by, injuring their shoulder. Your public liability pays their claim.
Examples are for illustrative purposes only. Compensation depends on the exact circumstances of the claim. No rights can be derived from these examples.
Your business insurance with Insify SmartGuide
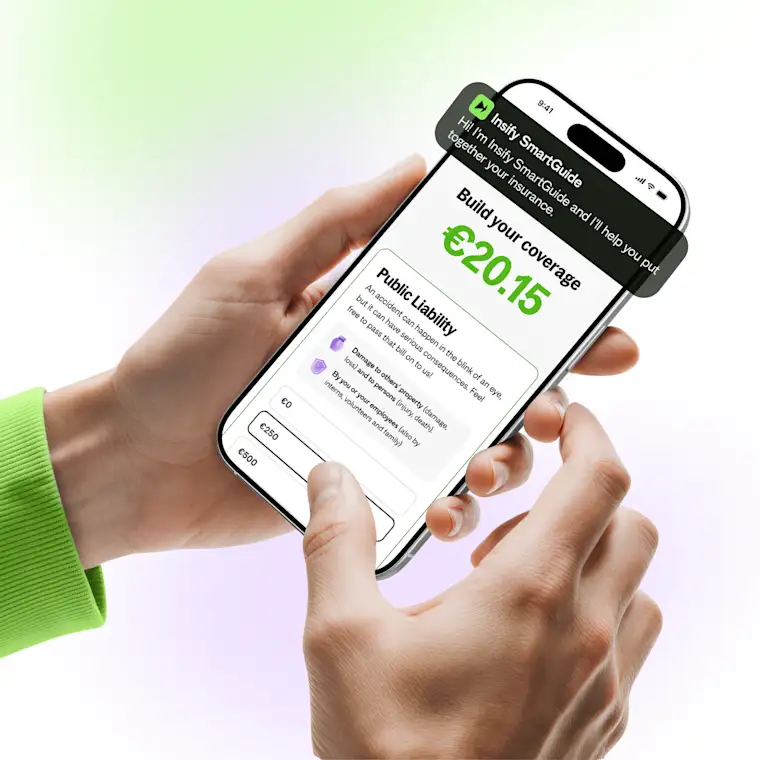
Taking out insurance can be quick. Making sure you have the right cover is another matter. With Insify SmartGuide, you don't sign a contract blindly. You ask all your questions, and get clear, immediate and personalised answers, before you take out a policy.
Are you covered if you accidentally damage a client's equipment while working?
What excess should you choose?
Are you protected in the event of a dispute with a client?
Insify SmartGuide guides you step by step to understand what's covered, what isn't, and why. In just a few clicks, you build insurance that's truly tailored to your business, with complete confidence. Try Insify SmartGuide. Understand your insurance before you need it.
How to choose the right insurance for a landscape business
Criteria to compare:
The cover. Check it covers what usually goes wrong on a landscaping job: injuries to people nearby, damage to other people's property, and damage to the property you're working on.
The limit. Check it matches what your clients ask for.
The price. Compare it together with the cover, the excess and the exclusions, not on its own.
The excess: This is the amount you pay yourself on every claim. Check it before you compare prices.
The exclusions: Read the ones for your trade, such as tree work above 3 metres and work on playgrounds. Work you have not declared is not covered either.
The staff. If anyone works for you, check whether employers' liability is included or costs extra.
More than 50,000 entrepreneurs trust us
When I had to make a claim, I was amazed how quickly and efficiently it was handled. Within a few days I had a resolution.
Very friendly, quick and thorough. It gives me real confidence in taking out the cover. The company feels genuinely transparent, exactly what I look for. You don't find that often.
Very friendly, quick and thorough. It gives me real confidence in taking out the cover. The company feels genuinely transparent, exactly what I look for. You don't find that often.
When I had to make a claim, I was amazed how quickly and efficiently it was handled. Within a few days I had a resolution.
The cover itself was sorted quickly, and when I later needed support I got that fast too.
Very friendly, quick and thorough. It gives me real confidence in taking out the cover. The company feels genuinely transparent, exactly what I look for. You don't find that often.
When I had to make a claim, I was amazed how quickly and efficiently it was handled. Within a few days I had a resolution.
The cover itself was sorted quickly, and when I later needed support I got that fast too.
Answers to your questions about our landscaping insurance
Public liability for a landscape business starts at €21.84 a month. Your price depends on your turnover, the work you do, how many people work in your business and the excess you choose. Get a quote online in a few minutes and see how a different excess changes your price.
Public liability is not required by law in Ireland. It is required by almost everyone who hires you. A main contractor will not sign you onto a site without a current certificate. Management companies want it before you maintain communal grounds. Local authorities and public tenders publish their own minimum limits. And when a claim does arrive, the cover is what stands between it and your own money.
Yes, up to 3 metres high. Trimming or felling a tree taller than 3 metres is not covered, and neither is work on playgrounds. If you take on that work, this policy won't cover it.
It depends on how the pipe or cable was involved in your work. If it is part of what you are working on, or necessarily involved in the job, it falls under cover for property in your care: €25,000 a claim on your own, €50,000 if more people work in the business. Other accidental damage to someone else's property is assessed under your public liability cover. Check service drawings before you dig.
Yes, for property that's part of the job: things you work on or are given to work on, things you can't avoid touching to do the job, and things you use to help you do it, like the client's ladder. Damage to these is covered up to €25,000 a claim, or €50,000 a claim if more than one person works in your business. The yearly maximum is twice that. Other damage to other people's property is covered up to €2.5 million a claim.
If a mistake in your work means another contractor's work has to be taken apart to reach it, the optional Faulty craftsmanship add-on pays to take it apart and put it back, with the same limits. It doesn't pay to fix your own work or materials.
Every landscaping policy comes with €2.5 million of cover a claim, and up to €5 million across the insurance year. It's the same for every landscape business we insure, so there's no limit to pick when you buy.
Your excess is the part of a claim you pay yourself. With a €500 excess on a €4,000 claim, you pay €500 and your policy pays €3,500. You can choose €0, €250, €500, €1,000 or €2,500, so you can pay nothing yourself on a claim. A higher excess usually means a lower premium. If your revenue is above €500,000, the options start at €500. The Faulty craftsmanship add-on has its own €500 excess.
Yes. Count everyone who works in your business, including owners, partners and seasonal crews. Once there's more than one of you, the limit for damage to the property you're working on, and for the Faulty craftsmanship add-on, goes up from €25,000 to €50,000 a claim. You can also add employers' liability, which covers claims from people who work for you if they're injured on the job, up to €13 million a claim.
Tell us all the work your business does, so your policy matches it. A few sign-up questions affect your price: whether you do fire-hazardous work, such as cutting, grinding or welding, and, if your business is less than 3 years old, whether you have at least 3 years of experience in the work. Others decide whether we can quote you online: if more than half your revenue comes from subcontractors and your revenue is above €500,000, if more than half your revenue comes from outside the EU, if an insurer has refused or cancelled your insurance in the last 5 years, or if there has been a situation involving a crime in the last 8 years. In those cases, contact us. Claims you already know about when your cover starts, or anything you know could lead to one, aren't covered.
Public liability covers injury and property damage caused by your work on site, including work you designed and built. It is not professional indemnity, which we do not offer for landscaping, so it does not answer for a client's financial loss from design advice alone, for example a scheme they say does not meet the brief.
Yes, if your business fits the policy's limits. Tell us how many people work for you and add employers' liability for your staff. The third-party property limit is €25,000 a claim for a one-person business or €50,000 if more than one person works in the business. The public liability limit is fixed at €2.5 million a claim and €5 million a year. It is built for businesses with up to 30 people and up to €10 million turnover.
Insurance guides for construction and trades
 InsuranceWhat does it cost a tradesman when a job goes wrong? Five years of real claims
A cable you could not see, a joint that was not quite tight, a ladder that slides. Real figures on how often things go wrong on the job in your trade, and what the bill looks like.
 InsuranceWhat is public liability insurance, and what does it cover?
Someone else gets hurt, or their property gets damaged, and they hold you responsible. Here is what sits inside it, what sits outside, and how the limit you pick changes the policy.
InsuranceWhat does it cost a tradesman when a job goes wrong? Five years of real claimsA cable you could not see, a joint that was not quite tight, a ladder that slides. Real figures on how often things go wrong on the job in your trade, and what the bill looks like.
InsuranceWhat is public liability insurance, and what does it cover?Someone else gets hurt, or their property gets damaged, and they hold you responsible. Here is what sits inside it, what sits outside, and how the limit you pick changes the policy.