Taxi driver insurance
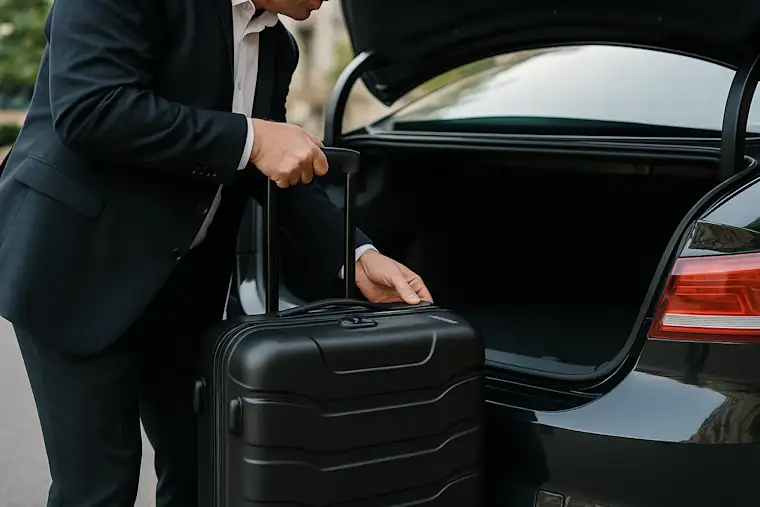
A passenger hurt getting out of the car, or a bag damaged in your boot. Your motor policy doesn't cover either, and both can result in a claim against you.
Public Liability from €7.55 per month, with cover up to €6.5 million per claim


Business insurance, done differently.

Fully online business insurance in Ireland.

A few questions and you're covered.

No lock-in, no long contracts.

Excess from €0, up to €6.5 million of cover.
Why take out business insurance as a taxi driver?
You're helping passengers and handling their belongings every day. Public liability can cover qualifying injury or property-damage claims arising from your insured taxi work.
Your cover depends on the circumstances. Compulsory motor insurance is required for your taxi. Passenger assistance and luggage handling depend on the circumstances and the policy's motor exclusions and exceptions. Being outside the car or not driving does not automatically make a claim a public liability claim.
Clients ask to see it. Public liability isn't required by law in Ireland. But airport and hotel contracts, corporate accounts and public tenders routinely ask you to show cover before they'll give you the work.
The help you need when a claim arrives. A claim for injury or property damage should be reported promptly. We assess it under your cover and handle qualifying defence costs and compensation, subject to the policy terms.
What is Public Liability insurance?
Public liability covers you when your work injures someone else or damages something that belongs to them. For a taxi driver that means the part of the job that happens outside the vehicle, and the passengers and property you are responsible for while they are with you.
How it works: if someone claims you caused injury or damage, Insify handles the claim and pays what is owed, up to your cover limit. Your excess is the part you pay yourself on each claim.
What it covers: injury to a passenger or a member of the public, damage to property belonging to someone else, and the legal costs of defending the claim.
Cover that fits your work: choose €1.25 million, €2.5 million or €6.5 million per claim. Council permits commonly ask for at least €2.6 million and public tenders often specify €6.5 million, so check what your contracts require before you pick.
Is it required?: Public liability isn't required by law in Ireland. However, many hotels, corporate clients, airport operators and school transport contractors require proof of cover before they'll give you work. Cover starts from €7.55 per month.
Who needs it: taxi drivers working ranks, airport runs, school or hospital contracts, and anyone carrying passengers' luggage, wheelchairs or equipment.

What does our insurance cover for taxi drivers?
Your public liability can cover qualifying injury and property-damage claims arising from your insured taxi work, subject to the policy's conditions.
Passengers and the public: claims involving passengers or members of the public may be covered where they fall within your insured activities and policy terms. An injury while entering or leaving the taxi is not automatically covered by public liability.
Property in your care: cover for property in your care is included for qualifying damage to passengers' property entrusted to you for handling, up to €5,000 per claim and €10,000 per insurance year. Loss or disappearance is excluded.
Damage to property at a pick-up or drop-off: a hotel door you catch with a case, or a glass panel you knock with a bag.
Staff, if you have them: you can add employers' liability up to €13 million per claim and per insurance year if you employ drivers or other staff.
What sits elsewhere: you still need appropriate motor insurance. Claims involving the use of a vehicle depend on the circumstances and the policy's motor exclusions and exceptions.

What's covered
Declared taxi and passenger-transfer work, subject to the motor exclusions and exceptions.
Business trips within your insured activity.
Use of your base, office or other premises for insured work.
Included cover for property in your care for qualifying handling damage, up to €5,000 per claim and €10,000 per insurance year.
Damage caused with or by a motor vehicle you drive or use. This does not apply to damage caused by items being loaded onto or unloaded from it. Each vehicle needs its own motor insurance.
Transport by water, rail or air.
Transport of animals or livestock.
Loss or disappearance of entrusted property. Included custody cover applies to qualifying damage under its handling conditions.
Cover and exclusions shown are indicative and non-contractual. Only the terms of your policy apply.
Some examples, for illustration
A passenger slips at the kerb while you help them out with their luggage and fractures a wrist.
A suitcase is crushed as you load it into the boot and the laptop inside is broken.
You catch a hotel's glass door with a luggage trolley while dropping a fare at the entrance.
A passenger slips at the kerb while you help them out with their luggage and fractures a wrist.
A suitcase is crushed as you load it into the boot and the laptop inside is broken.
You catch a hotel's glass door with a luggage trolley while dropping a fare at the entrance.
Examples are for illustrative purposes only. Compensation depends on the exact circumstances of the claim. No rights can be derived from these examples.
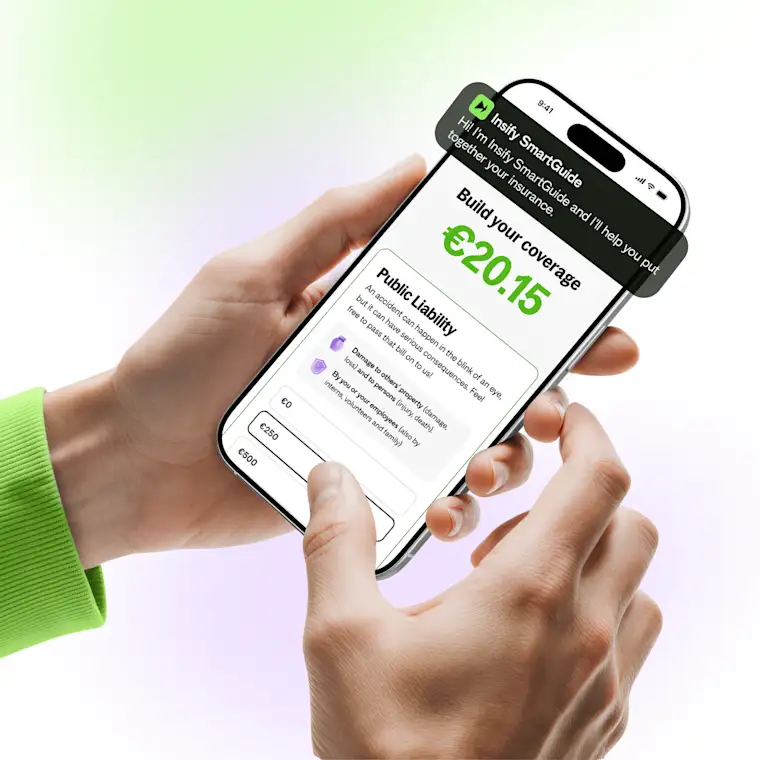
Your business insurance with Insify SmartGuide
Taking out insurance can be quick. Making sure you have the right cover is another matter. With Insify SmartGuide, you don't sign a contract blindly. You ask all your questions, and get clear, immediate and personalised answers, before you take out a policy.
Are you covered if you accidentally damage a client's equipment while working?
What excess should you choose?
Are you protected in the event of a dispute with a client?
Insify SmartGuide guides you step by step to understand what's covered, what isn't, and why. In just a few clicks, you build insurance that's truly tailored to your business, with complete confidence. Try Insify SmartGuide. Understand your insurance before you need it.
How to choose the right insurance as a taxi driver?
Criteria to compare:
The cover offered: check the policy follows the whole job, not just time behind the wheel. Airport runs, rank work, school and hospital contracts, wheelchair-accessible work and handling passengers' luggage should all be declared and all be covered.
The price: compare premiums across insurers, but an attractive price can hide exclusions that matter in passenger transport. Read what is carved out before you compare the monthly figure.
The excess: know what stays at your own expense when a claim happens, and check whether it changes by claim type. It is the number people notice only after an incident.
The exclusions: watch for undeclared work, licence and permit conditions, transport outside the categories you declared, and anything the policy treats as belonging to a motor policy instead.
The service: in passenger transport an incident can happen at any hour. Choose an insurer that is reachable and that knows the sector. At Insify, our online support team knows the specifics of your work.
Mistakes to avoid: do not take a generic policy that ignores what passenger transport actually involves, and do not assume your motor cover answers for everything that happens on a job. To secure your business today, discover our Public Liability insurance.
More than 50,000 entrepreneurs trust us
When I had to make a claim, I was amazed how quickly and efficiently it was handled. Within a few days I had a resolution.
Very friendly, quick and thorough. It gives me real confidence in taking out the cover. The company feels genuinely transparent, exactly what I look for. You don't find that often.
Very friendly, quick and thorough. It gives me real confidence in taking out the cover. The company feels genuinely transparent, exactly what I look for. You don't find that often.
When I had to make a claim, I was amazed how quickly and efficiently it was handled. Within a few days I had a resolution.
The cover itself was sorted quickly, and when I later needed support I got that fast too.
Very friendly, quick and thorough. It gives me real confidence in taking out the cover. The company feels genuinely transparent, exactly what I look for. You don't find that often.
When I had to make a claim, I was amazed how quickly and efficiently it was handled. Within a few days I had a resolution.
The cover itself was sorted quickly, and when I later needed support I got that fast too.
Our answers to your questions about taxi public liability insurance
No. You need appropriate motor insurance for the vehicle. Public liability concerns qualifying claims for injury or damage caused to other people through your business, subject to the policy's motor exclusions and exceptions. Passenger assistance and loading or unloading cannot be assigned to one policy simply because the taxi was parked or you were outside it.
Public liability isn't required by law in Ireland. However, many hotels, corporate clients, airport operators and school transport contractors require proof of cover before they'll give you work. Cover starts from €7.55 per month.
Cover starts at €7.55 per month including taxes. Your price depends on your turnover, the limit and excess you pick, and whether you add employers' liability for staff. A driver working alone on street and rank work sits at the lower end. Someone on airport contracts with a second driver and a €6.5 million limit pays more. Run a quote to see yours. It takes 2 minutes, with no commitment.
It depends on the circumstances. An injury while a passenger enters or leaves the taxi can involve the use of the vehicle, so it is not automatically a public liability claim. Report the incident so it can be assessed against the relevant motor and public liability cover. Your policy's terms, limits and excess apply.
Custody and care cover is included for qualifying damage to property entrusted to you for handling, up to €5,000 per claim and €10,000 per insurance year. The limit is per claim, not per item. Loss or disappearance is excluded. Claims involving the vehicle are also subject to the policy's motor exclusions and exceptions.
Cover can apply to your declared taxi work at airports, ranks, hotels and other business locations in Ireland, subject to the policy's conditions and territorial limits. For taxi activities, work outside Ireland is not covered. Vehicle-related claims remain subject to the motor exclusions and exceptions. Check the activities and conditions in your quote before buying.
The excess is the part of every claim you pay yourself before Insify pays the rest. If your excess is €500 and a claim settles at €3,250, you pay €500 and Insify pays €2,750. For turnover up to €500,000 you can choose €0, €250, €500, €1,000 or €2,500, and €500 is the default. A higher excess lowers your monthly premium but costs you more on the day something happens, so choose the figure you could actually pay at short notice rather than the one that makes the quote look best.
Yes. There is no long-term commitment and you can cancel anytime. You can also change your cover limit, adjust your excess or add employers' liability as your business changes, without starting a new policy. If you take on a second driver, add a contract that requires a higher limit, or stop doing a type of work, update the policy at that point. Keeping it current is what makes sure a claim is paid, and it takes a few minutes online.